Debt Consolidation When One Loan Has Only 6 EMIs Left: Compare the Real Cost
Should you include a nearly finished loan in debt consolidation? Compare remaining EMIs with a new loan’s total cost, fees and tenure using a practical Indian example.
Master your credit score, learn smart debt strategies, and unlock resources to make borrowing simpler, faster, and more affordable.
Should you include a nearly finished loan in debt consolidation? Compare remaining EMIs with a new loan’s total cost, fees and tenure using a practical Indian example.
Need money before payday? Compare an employer salary advance with an instant personal loan using total cost, fees, next-salary impact and a practical ₹20,000 example.
Debt consolidation replaces selected debts with a new repayment plan, while loan settlement is a negotiated resolution that may affect credit reporting. Compare full costs, written terms and next steps before deciding.
If you need an instant personal loan but do not have a salary slip, learn which alternative income records a lender may consider, how to check EMI affordability and how to compare loan terms safely.
Juggling revolving credit-card dues and personal-loan EMIs? Learn how to compare a consolidation offer against the remaining cost of your current debts without mistaking a lower EMI for a saving.
Working on a fixed-term or contract basis and need an instant personal loan? Learn which income and employment records may help, how to assess affordability, and what to check before submitting a formal application.
Have multiple loans and want one manageable repayment? Compare debt consolidation with a personal-loan balance transfer using total cost, tenure, fees, EMI and credit considerations before choosing.
A practical debt-consolidation guide for doctors and medical professionals covering EMI affordability, total cost, CIBIL impact, KFS checks and repayment risks.
Looking for an instant personal loan as a Chartered Accountant? Learn what lenders may verify, documents to prepare, EMI affordability and safe comparison steps.
Have multiple EMIs as a government employee? Learn when loan consolidation may help, how to compare total cost, and how to avoid extending debt unnecessarily.
Looking for an instant personal loan as a nurse? Learn what lenders may check, which documents to prepare, how to estimate EMI and how to compare the real cost before applying.
Managing multiple EMIs as an IT professional? Learn when loan consolidation may help, how to compare total cost, and how to protect your credit profile.
Need an instant loan as a government employee? Learn what to check before applying, how KFS and APR help compare offers, and how to estimate EMI safely.
Government teacher with multiple EMIs? Learn how debt consolidation can simplify repayments, what to compare, and how to avoid increasing your total loan cost.
Looking for an instant personal loan as a doctor? Learn how salaried and self-employed doctors can prepare income, KYC and professional documents before applying.
Your first personal-loan payment may differ from the regular EMI. Learn why broken-period interest can change the first payment, how to calculate it, and what to check in your loan documents.
Changed your salary or bank account? Learn how to update the NACH or e-mandate used for your personal-loan EMI, avoid missed debits, and verify the new mandate before the next due date.
Compare personal loan offers without applying everywhere. Learn how to shortlist lenders, use KFS and APR, calculate total cost, and avoid unnecessary credit enquiries.
A practical guide to gold-loan auction risk, borrower notices, sale proceeds, and the steps to take before an auction deadline.
Need cash but have a fixed deposit? Compare borrowing against the FD with premature closure using interest, lost returns, fees, liquidity and repayment risk before deciding.
A loan marked 'settled' is not the same as a loan marked 'closed'. Learn what the two statuses mean, how settlement can affect future borrowing, and what you can do if you later repay the waived amount.
Not every mutual fund qualifies for a loan. Learn how lender-approved schemes, LTV, NAV risk and pledge rules affect your LAMF eligibility.
How many CIBIL enquiries are too many? Learn what lender enquiries mean, why repeated applications can matter, and how to apply for loans carefully.
Personal loan approved but money not credited? Learn what approval means, why disbursal can be delayed, what to check and how to escalate safely.
Should you prepay your personal loan or invest extra cash? Compare loan cost, liquidity, risk and emergency savings with a simple ₹1 lakh framework.
How is Loan Against Mutual Funds interest calculated? Learn daily interest, repayment options, fees, NAV risk and a practical ₹3 lakh example.
Gold loan or personal loan? Compare cost, EMI, collateral risk, fees and repayment structure with a practical ₹3 lakh example before you borrow.
Thinking about moving your personal loan to another lender? Learn how to compare rates, fees, tenure and break-even savings before transferring your balance.
Took a digital loan and changed your mind? Learn RBI cooling-off rules, exit costs, timelines and what to check in your KFS before cancelling.
Closed your personal loan but CIBIL still shows it as active? Learn the 2026 reporting cycle, what to check and how to dispute errors.
Before signing a personal loan, learn what the RBI Key Facts Statement shows, how APR differs from interest rate, and which fees and terms to check.
Missed an EMI? Learn how RBI penal charges work, why penal interest is different, what lenders can charge, and how to check your loan statement.
Personal loan interest is not automatically tax-deductible. Learn when the loan purpose may qualify, what Section 24(b) covers, and what documents to keep.

Learn how Loan Against Mutual Funds works, how pledging restricts redemption, what happens when NAV falls, and what to check before borrowing.
Checking your own CIBIL Score does not lower it. Learn the difference between self-checks and lender enquiries before applying.
Checking your own CIBIL Score does not lower it. Learn the difference between self-checks and lender enquiries before applying for a loan.
Need extra cash while repaying a personal loan? Learn top-up eligibility, EMI, fees, FOIR impact and how to compare a top-up with a fresh loan.
Found a wrong loan, overdue entry or enquiry on your CIBIL report? Learn how to dispute it, track correction timelines and understand RBI’s ₹100-per-day compensation framework.
Loan closed but your lender has not returned the original property documents? Learn RBI’s 30-day rule, ₹5,000-per-day compensation for lender-attributable delays, charge removal requirements, and what borrowers should do next.
Learn how to read a personal loan repayment schedule, understand principal and interest in each EMI, calculate total loan cost, and see how prepayments change the balance.
A practical guide to personal-loan documents in India: identity, income, bank statements, employment details and why lenders may ask for additional verification.
Compare a loan against mutual funds with a personal loan on collateral, cost, repayment and market risk, with a practical ₹5 lakh borrowing framework.
Before taking a personal loan, check how much cash you should keep aside for emergencies. A practical Indian framework for EMI, essential expenses and borrowing safely.
Yes, you can have two personal loans at once, but approval depends on income, existing EMIs, credit history and lender policy. Learn how to calculate the real repayment burden before applying.

Making a single lump-sum prepayment or paying just one extra EMI each year can slash your loan tenure by years and save you ₹5 lakhs or more in interest. Here is how loan prepayment math actually works, the RBI rules on zero penalty charges, and the exact strategies to become debt-free faster.

A personal loan advertised at 10.5% may cost more than it looks. Learn the difference between the interest rate and APR, what fees to check in your Key Fact Statement, and how to compare the real cost of two loan offers.

Diwali spending doesn't have to mean expensive debt. Follow Ritu's real-world budgeting story to see exactly how to plan, borrow, and repay a personal loan smartly this festive season — with concrete numbers, a lender comparison, and a prepayment strategy that can save you thousands.

दिसंबर में फ्लाइट और होटल महंगे हो जाते हैं। जानिए न्यू ईयर ट्रिप का बजट कैसे बनाएं, पैसे कैसे बचाएं, और ज़रूरत पड़ने पर ट्रैवल के लिए पर्सनल लोन कैसे समझदारी से लें।

Diwali spending is surging this year, driven by young, first-time borrowers and easy BNPL credit. Here's a real decision framework — not just a loan pitch — for how much to budget, how to fund the gap, and how to keep the celebration from becoming a January debt hangover.

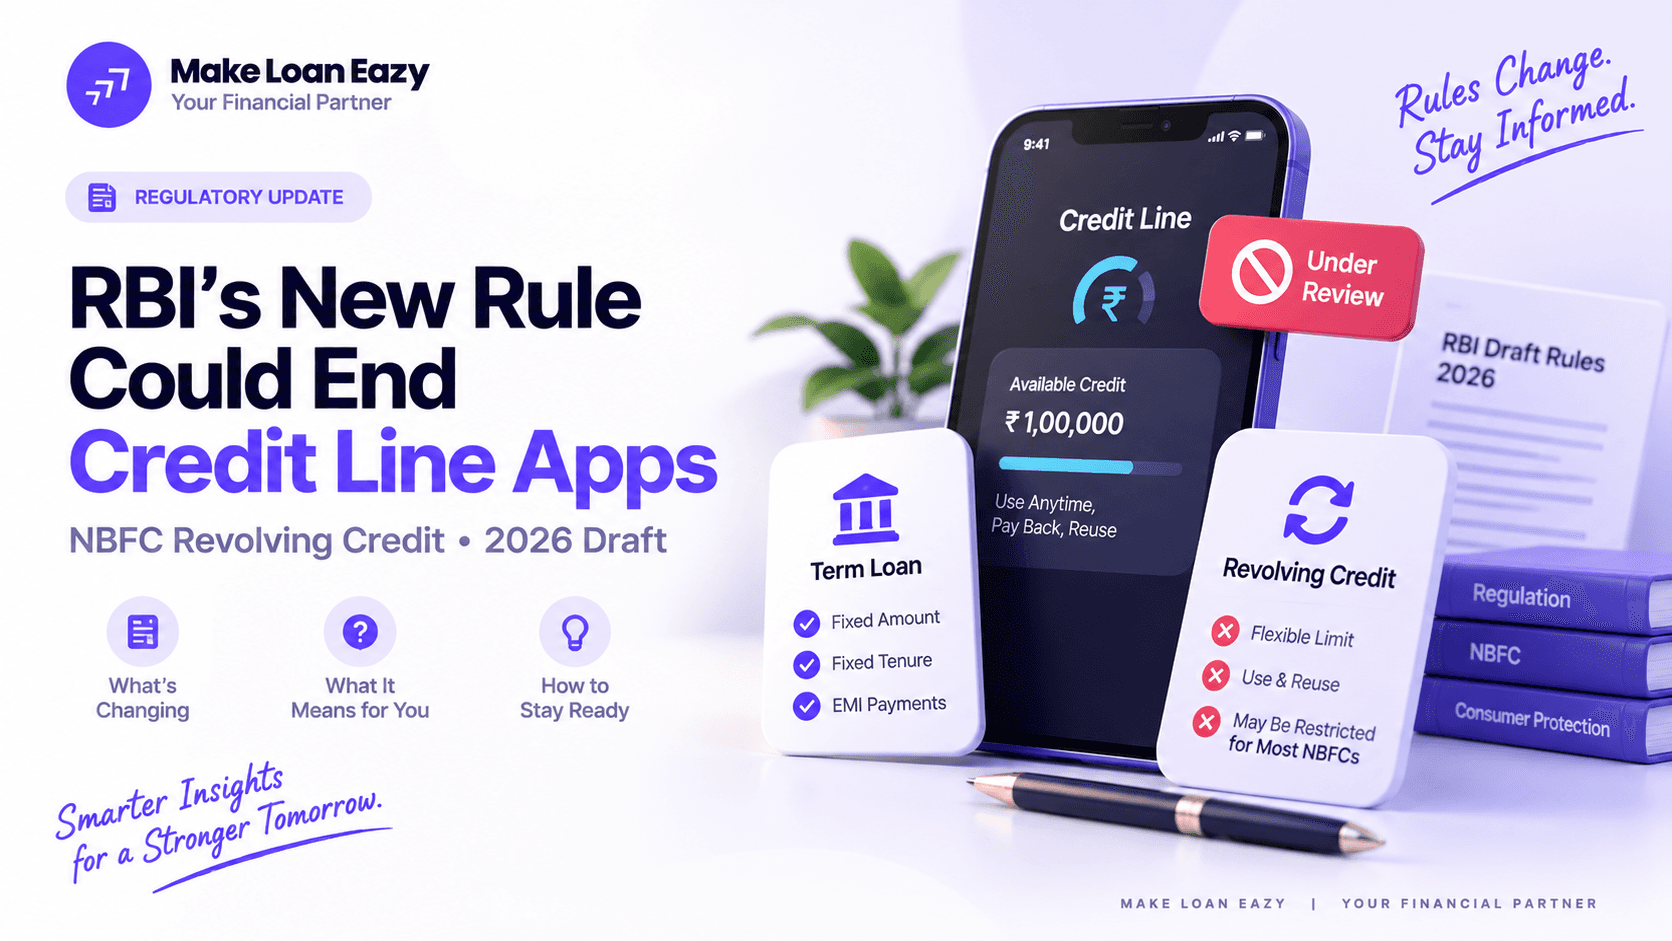
RBI's new draft could force NBFCs to stop offering "credit line" apps, flexi loans, and overdraft-style facilities altogether — restricting them to fixed term loans instead. Here's exactly what's changing, why, and what it means if you use one.

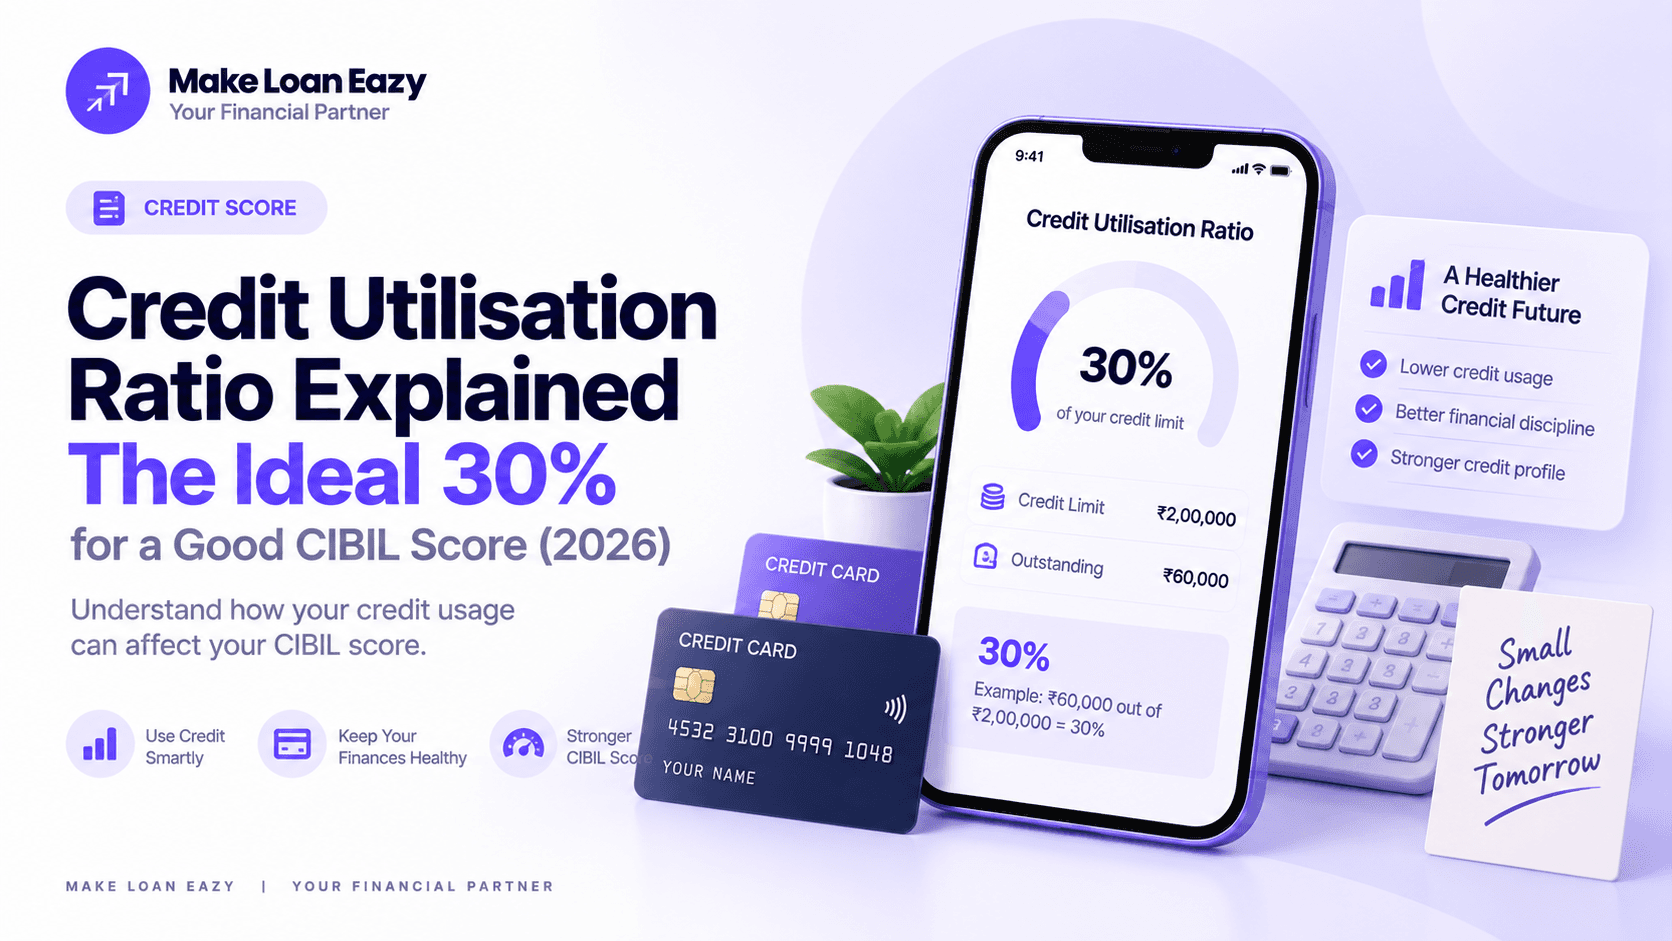
Your credit utilisation ratio is one of the biggest levers on your CIBIL score — and most people don't even know they're pulling it wrong. Here's what it is, the ideal percentage, and simple ways to bring it down.

FD, mutual funds, or shares — which should you pledge for a loan? Here's the real comparison on cost, risk, and speed, with a worked ₹5 lakh example, so you can borrow without selling what you own.
Fake loan apps are trapping Indian borrowers with hidden fees and data misuse. Here's the simple, step-by-step way to check if a loan app is really backed by an RBI-regulated bank or NBFC before you apply.
A new RBI draft could freeze your lender's markup on floating-rate personal loans for three years and force personal loan rates onto an external benchmark. Here's exactly what changed, what's still a draft, and what to do now.
Swipe your credit card or take a personal loan? The wrong choice can cost you tens of thousands of rupees in extra interest. Here's the real cost comparison, worked examples, and a simple checklist to help you decide.
Most personal loan rejections come down to five checkable things: age, income, job stability, credit score, and existing debt. Here's exactly what Indian lenders look for in each, and how to fix weak spots before you apply.
Your Loan Against Mutual Funds isn't risk-free just because you're not selling anything. Here's exactly what a margin call is, how it unfolds day by day, and how to avoid getting caught off guard when markets fall.
CIBIL reporting is faster in 2026. Learn the new reporting dates, why your score is not instant, and what to do after paying an EMI or fixing an error.

Can a bank really lock your phone for missing an EMI? Under RBI's new 2027 rules, yes — but only for the loan that financed that exact device, and only after strict time-gated conditions. Here's a full walkthrough with a worked example.

Personal loans used to mean emergencies. That's changing — more young Indians are now borrowing deliberately for weddings, renovations, and big purchases without touching their savings. Here's how to do it without it becoming a mistake.

Before approving your loan, lenders run one number that decides how much you can borrow: your FOIR. Here's what it is, how to calculate it yourself, and how to improve it before you apply.

The RBI has issued a sweeping new code governing how banks and recovery agents can chase overdue loans, effective January 1, 2027. Here's exactly what's banned, what's still allowed, and what to do if you're facing harassment.

RBI's new rules mean most floating-rate loans taken by individuals can now be prepaid or foreclosed with zero penalty. Here's exactly who's covered, what to check before you prepay, and how it changes the math on paying off your loan early.

Your CIBIL score decides whether you get approved for a loan and how much interest you pay. This guide breaks down the score range, what actually moves it, the newest RBI rules protecting borrowers, and a step-by-step plan to raise it.

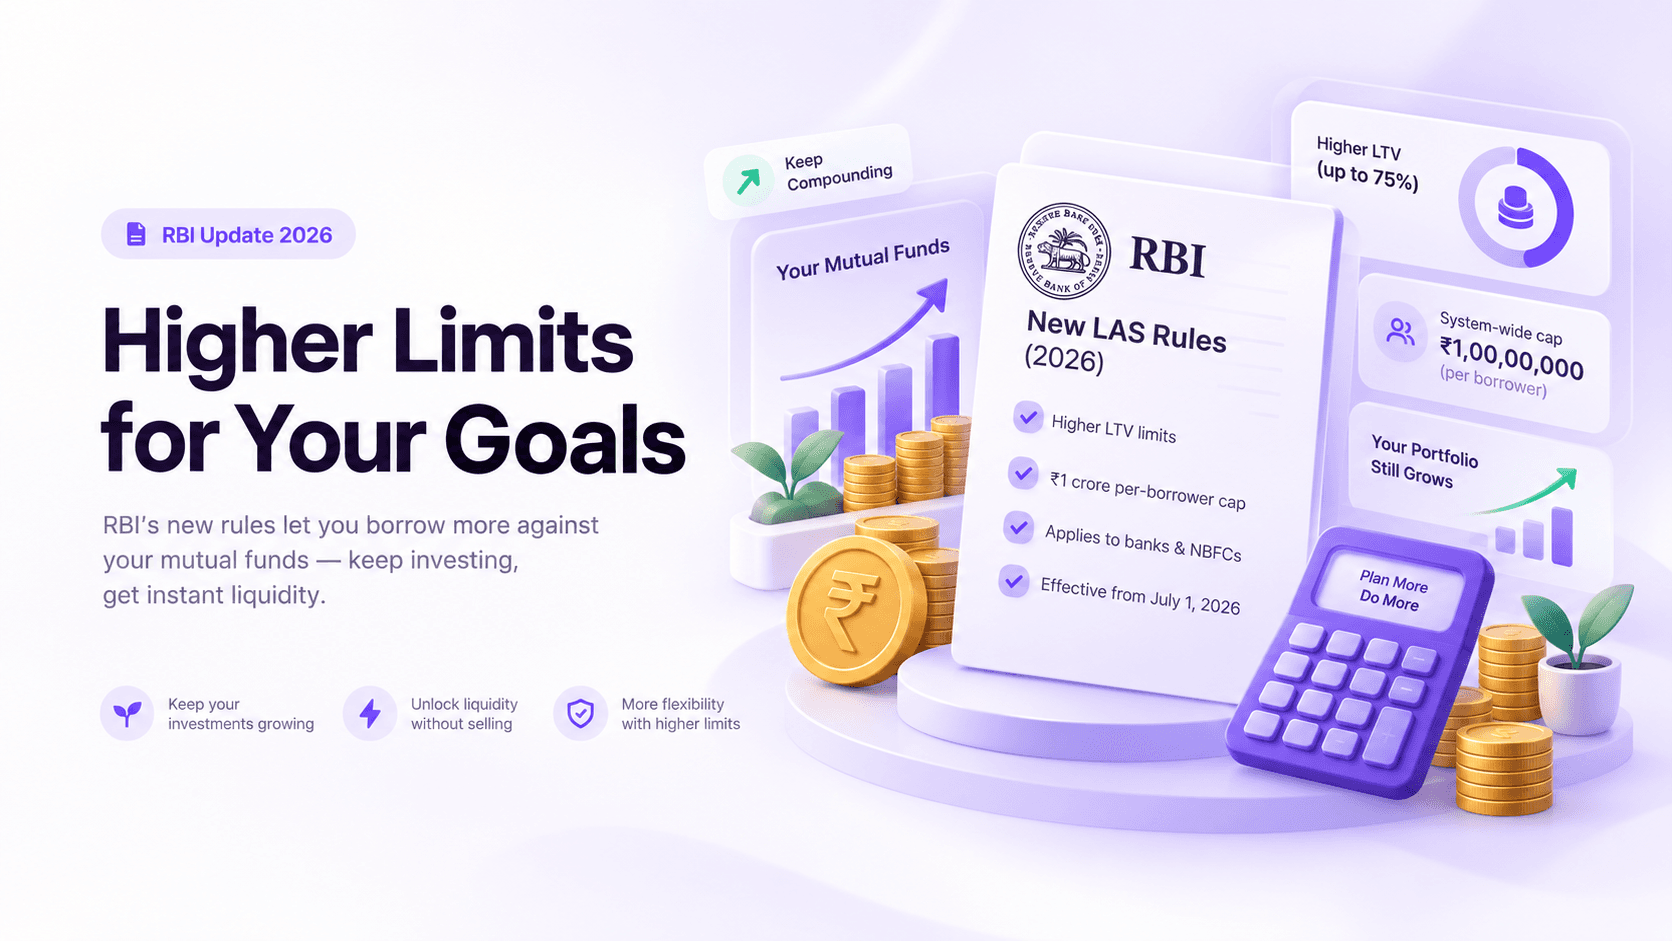
RBI has raised how much you can borrow against your mutual funds, with new rules taking effect July 1, 2026. Here's exactly what changed, what it means for your LAMF loan, and how it compares to a personal loan.

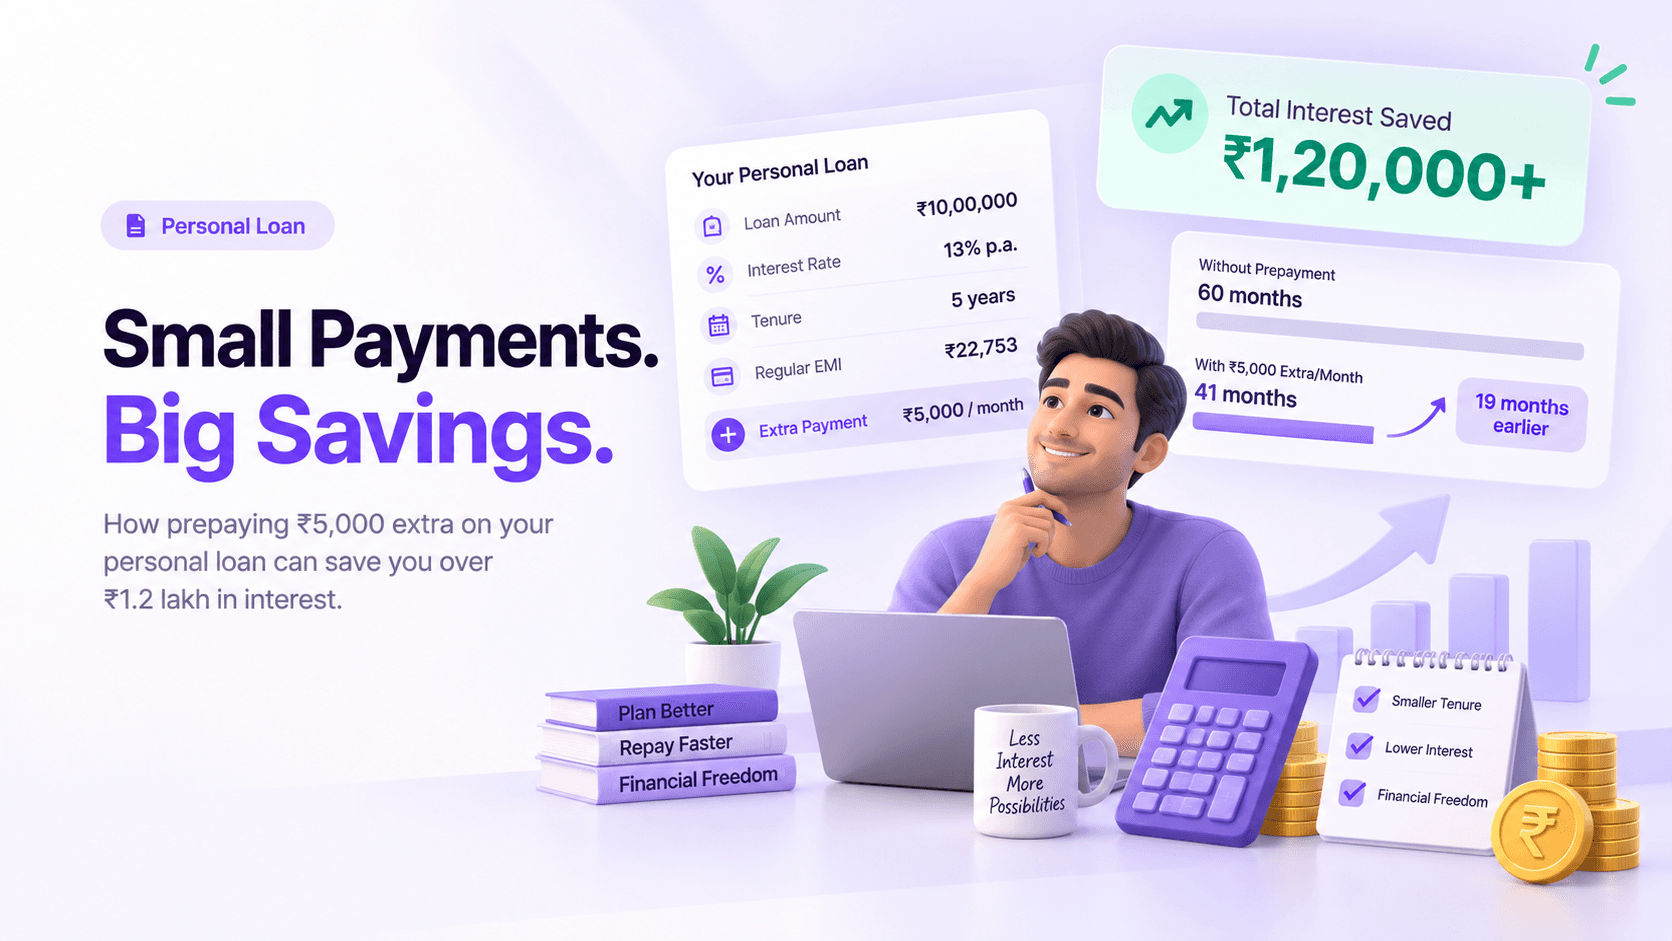
A small, consistent extra payment on your personal loan EMI can shrink your tenure by years and save you lakhs in interest. Here's the math, the method, and the mistakes to avoid.